Author Archives: Maddi Travers

Small Caps Take the Lead: A Decade in the Making

Small caps are quietly having a breakout year, outperforming large caps calendar year to date by roughly 9%. Understandably, this data point has slipped under the radar as investors are caught up in attention-grabbing headlines about artificial intelligence, war, inflation and high interest rates. It’s been ten years since small cap indices in the US saw meaningful outperformance relative to large — we believe this could be the beginning of a much longer-term trend1.

Two forces driving the shift

Small cap outperformance, relative to large cap, this year is driven by two intertwined factors. First, investors may be growing sceptical of the hundreds of billions being poured into AI data centre buildouts with questionable economics. Second, earnings growth is broadening — most forecast S&P 500 earnings growth is now coming from the broader market, not the handful of mega-cap tech names that dominated 2023–2025. It’s refreshing to see stock prices rewarding small cap earnings growth.

Small caps’ lost decade

Small caps have faced a difficult decade, and we have the scars to prove it. Tariffs, trade wars, COVID lockdowns, wars (Russia/Ukraine and US/Iran), deglobalisation, inflation and high interest rates have made for a tough backdrop for smaller businesses, which tend to rely on business confidence and a stronger economy to perform well.

At the same time, economic value has flowed to mega-cap businesses, driving significant concentration in benchmarks, particularly in the US. Recent research shows the S&P 500 hasn’t been this concentrated, measured by its top five companies, since the early 1970s2.

What the Nifty Fifty can teach us

Students of financial history will remember the 1970s as the “Nifty Fifty” era: the idea that investors should own the same 50 blue-chip growth stocks and watch their wealth compound. The largest five companies at the time were IBM, AT&T, General Motors, Exxon, and Eastman Kodak, making up roughly 25% of the S&P 500. That basket traded at a significant premium to the broader market, and the bubble eventually popped. It’s always hard to pin a clear catalyst on a bursting bubble, but most point to a controversial Republican president (Nixon) introducing a 10% import tariff, combined with an oil crisis, as the trigger that made markets wobble.

Today’s top five

Studying prior eras of concentration unwinding, we find they tend to coincide with smaller companies outperforming — as seen after the Nifty Fifty era and after the dot-com bubble. As of June 2026, the largest five companies were Nvidia, Apple, Alphabet (Google), Microsoft, and Amazon, making up a little over 25% of the S&P 500. All iconic businesses, ubiquitous in our everyday lives, and likely AI winners.

You don’t need to be bearish on individual large caps to be bullish on small caps. We’re simply observing that market broadening has historically been a significant tailwind for smaller-company returns.

Why we like the setup

We find the current setup for small caps attractive from an allocation perspective. We’re also seeing more investors use small caps to diversify away from technology-heavy large-cap indices. Small caps offer greater exposure to the real economy, which is seeing encouraging growth across a range of industries after years of subdued growth — driving earnings forecasts higher.

For investors currently on the sidelines, we encourage you to take a closer look at an asset class showing the hallmarks of an attractive entry point.

References
1. Source: Russell 2000 vs S&P500.
2. Source: Bloomberg Finance LP, Deutsche Bank. 30 June 2026

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only.


This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. In addition, this material represents only the views of the Paradice Global Small Cap team as at the time of release and is not intended, and may not, represent the views of Paradice or any of the other investment teams at Paradice. Past performance is not a reliable indicator of future performance.


It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.
The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.


The information and opinions contained herein, including information obtained from third party sources which are considered to be reliable, are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.
Contributors:

Paul Mason
Further Information

The Empty Side of the Field

Watching Messi score his first World Cup hat-trick recently, I found myself thinking back to weekends spent watching my kids play soccer.

At that age, the game is wonderfully simple. Wherever the ball goes, every kid follows. Half the field sits empty. Coaches shout, parents laugh.  Everyone’s watching the ball.  Nobody pays attention to the empty space.

Today’s stock market isn’t so different.  Attention is finite. Wherever it flows, something else gets left behind. Every crowded trade creates a neglected one — two sides of the same field.

Over the past year, investors have been captivated by artificial intelligence, and for good reason. We think AI is one of the most important technological developments of our lifetime, and the companies building the infrastructure behind it have created real value. In many cases, the attention is deserved.

 Earlier this year, when geopolitical tensions in the Middle East triggered a sharp correction in semiconductor stocks, we saw opportunity rather than risk. We expressed our view to investors at an event in Brisbane: the long-term demand drivers hadn’t changed just because markets had gotten nervous. So, we added to several positions, a decision that is so far looking positive. If anything, we could have leaned in harder.

Our conviction in AI hasn’t changed. Where we’re finding the next opportunity has.


Attention Has Become Exceptionally Concentrated

Investor Rob Arnott put it well: “When bubbles start in one place, there’s an anti-bubble somewhere else.”

Whether today’s AI trade becomes a bubble isn’t really the point. When everyone runs toward one opportunity, something else gets left behind — and that’s where we’re increasingly looking.

The numbers make the concentration hard to ignore. Semiconductors alone accounted for nearly 55% of global equity market returns this year. Add technology hardware and that climbs past 80%. Include industrial companies benefiting from AI infrastructure spend, and roughly 96% of total market gains came from just three industry groups1. 

Thousands of listed companies compete for capital every day. Almost all of the market’s gains came from a narrow slice of it.

What happened elsewhere is just as telling. Software, consumer discretionary and healthcare all detracted from market2. 

The market hasn’t simply turned enthusiastic about technology —based on recent outcomes, the market has been driven by one part of technology: the companies supplying the picks, shovels and infrastructure powering AI.


Looking for Open Space

None of this means the AI story is over. We still own businesses benefiting directly from AI infrastructure spending, and we remain optimistic about their long-term prospects.

But investing isn’t about identifying yesterday’s winners. It’s about identifying tomorrow’s.

As capital keeps crowding into the same handful of industries, we’re finding more to like elsewhere — businesses with large addressable markets, disruptive models, and founders still running the show. Regardless of what happens with AI, we believe these businesses can keep compounding value for years.

They rarely make headlines. They’re not discussed endlessly on financial television, and they’re rarely at the centre of the conversation.  In our view, the most attractive investments rarely begin with consensus. They begin with neglect.

 The crowd is still chasing the ball. We’re looking at the space they’ve left behind.

1 & 2. MSCI ACWI All Cap Index calendar year to 30 June 2026 contributions to return.

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only.

This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. In addition, this material represents only the views of the Paradice Global All Cap team as at the time of release and is not intended, and may not, represent the views of Paradice or any of the other investment teams at Paradice. It does not reflect any events or changes in circumstances occurring after the date of publication

It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward-looking statements. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.

The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

The information and opinions contained herein, including information obtained from third party sources which are considered to be reliable, are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.

Contributors:

Munish Malhotra

Further Information

Australian Banks: The Bull Market Is Over

The Regime Change: From Bull to Bear

Typically rising interest rates are good news for the major banks up to a point, as higher rates widened margins and, in our view drove the earnings growth that contributed to higher valuations. That changed in April.


We believe the sector has reached a turning point. Rate rises that previously supported earnings are now eroding credit quality as suggested by additional bank provisions. Following on from this, the same environment that drove upgrades is arguably now the source of the risk.


In our view, this isn’t just a cyclical shift. The federal government’s proposed changes to negative gearing and CGT on investment property, if implemented, could make things worse — speeding up earnings decline that was already starting to show in the numbers.

Policy Shock: Negative Gearing and CGT Reform

The government’s proposed changes to negative gearing and CGT have fundamentally altered the economics of residential property investment.

Based on recent industry discussions, for investors, removing the negative gearing tax benefit may be broadly equivalent of a 1–1.5% increase in their funding costs. Put another way, it could reduce what they can afford to pay for an established property by around 25%. That’s a significant shift, not a minor adjustment.

We do not expect new dwellings to fill the gap. They typically generate lower capital gains, which makes them far less appealing to investors chasing total return. Nor do we expect demand to simply rotate from established to new stock.

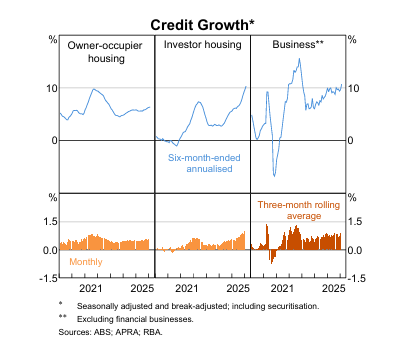
Chart 1

Chart 1: Investor credit growth has been flying. That is about to change. The removal of negative gearing benefits represents an effective increase of 1–1.5% in investor funding costs, or equivalently a ~25% reduction in the price investors can afford to pay for established property.

What This Means for Housing

When investors pull back, turnover typically falls. And investor participation has been the engine of the housing market — they are currently estimated to account for around 40% of new lending flow, despite being only 20% of the banks’ back book, informed by recent property industry discussions. That gap highlights how important they’ve been to volume growth over the past two years.

We expect investor credit growth may slow from 7–8% today to around 3–4% as investor flow trends toward zero, informed by these same industry discussions. We are already seeing a negative effect on house prices with the prospect of prices remaining subdued for some time. Fewer buyers, higher effective costs and stretched affordability, may not leave much room for prices to hold up.

What This Means for the Banks

Lower house prices, slower credit growth and higher interest rates are generally a difficult combination for bank earnings. We expect downgrades may occur in coming quarters. How severe they are will depend on where rates and credit growth settle — but the direction appears clear.

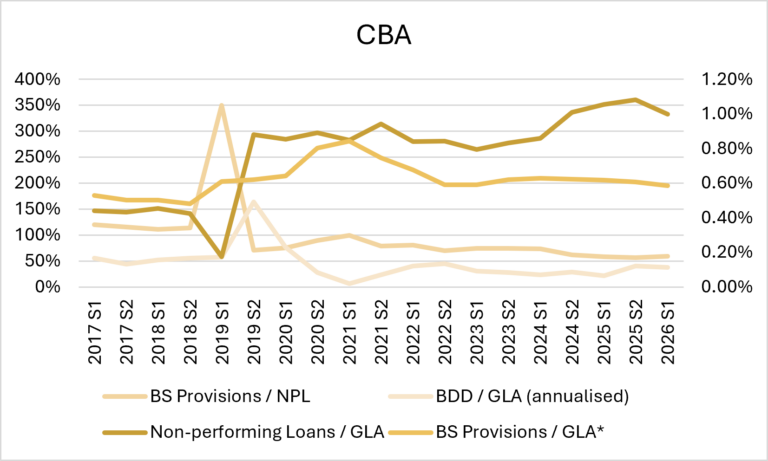
On credit quality, the banks will tell you their provisioning is adequate. We don’t agree — except in the most benign outcomes. Using CBA as an example, non-performing loans have been rising for four consecutive halves. The reason this hasn’t yet translated into actual losses is straightforward: high house and other asset prices have meant borrowers in difficulty could sell and cover their obligations. No forced sales, no losses.

As prices fall, that stops being true. Financial stress will likely rise, provisioning may need to follow, and the cycle will begin to resemble previous ones.

Chart 2

Chart 2: Paradice, CBA Non-performing loans to gross loans and acceptances have been elevated since post-COVID. These have not resulted in ultimate losses principally as a result of elevated asset (house and other) prices. As those prices retreat, this buffer disappears.

Valuation

At the time of writing, the banks are trading at 1.5–3.5x book value. That’s hard to justify in a stable environment. In a deteriorating one, it’s arguably very hard to justify. When you stress-test returns on equity against lower volumes, margin pressure and higher impairments, valuations closer to book value may look more appropriate.
Earnings downgrades could put a spotlight on these multiples. When both earnings and valuation move against you at the same time, a re-rating often tends to be swift.

In Summary

The proposed changes to negative gearing and CGT are, in our view, bad for the domestic economy and, by extension, for the Australian banking sector. We are cautious on the sector and recommend an underweight position relative to benchmark.

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only. This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. In addition, this material represents only the views of the Paradice Australian Equities team as at the time of release and is not intended, and may not, represent the views of Paradice or any of the other investment teams at Paradice.


It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.


The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.


The information and opinions contained herein, including information obtained from third party sources which are considered to be reliable, are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.

Table of Content

Contributors:

Julia Weng

Further Information

Capturing Alpha: How Long/Short Strategies Can Improve Total Portfolio Outcomes

The Problem with Long-Only in a Concentrated Market

For Australian investors, the challenge of generating consistent excess returns in long-only equity has become increasingly apparent. The ASX 200 is dominated by a handful of large financials and resources companies, and the performance of the broader index is often driven by a small number of names. Managers who are underweight these names for fundamental reasons can find themselves persistently dragging on relative performance—not because their views are wrong, but because the benchmark composition works against them.

This is compounded by a global trend. As Goldman Sachs Prime Services noted in their June 2025 analysis, traditional active equity managers globally have struggled materially in recent years1, with the average fund underperforming its benchmark by 1.5% in 2024 alone. The concentration of market returns in the largest stocks has been cited as a significant contributing factor2.

Active extension strategies offer a structural response to this challenge—not bytaking more market risk, but by expanding the universe of alpha opportunities available to the manager.

The Mathematics of Extended Alpha

Consider a skilled manager with genuine stock-selection ability. In a long-only portfolio, that skill can be applied to long positions only. In an active extension fund—say, a 135/35—the same manager can express views on approximately 170% of the portfolio’s capital. This does not change the fund’s net market exposure (which remains at 100%), but it dramatically increases the number of active positions contributing to alpha.

The Morgan Stanley research framework describes this as expanding the “alpha hunting ground.” Their analysis demonstrated that the additional tracking error generated by a 35% active extension is modest—rising from approximately 3.5% for a long-only portfolio to around 4.3%—while the potential uplift in portfolio alpha can be more notable3.

For an Australian fund benchmarked to the ASX 200, this is a meaningful consideration. The short book can be used not just to express negative views on individual stocks, but to reduce sector concentrations, offset factor tilts (such as inadvertent value or small-cap biases in the long book), and facilitate pair trades between related names. These are tools that long-only managers simply do not have.

The Fund-Level Impact

One of the most compelling arguments for active extension strategies—and one that is often underappreciated—is the fund-level risk arithmetic.

For most institutional and high-net-worth portfolios, the dominant source of volatility is equity beta. Whether a portfolio holds 50% or 70% in equities, the co-movement of those holdings with the broader market typically accounts for 90% or more of total portfolio volatility. This means that incremental tracking error from an active equity strategy—which by definition is uncorrelated with the market beta—is largely absorbed at the total portfolio level.

In practice, moving from a long-only active equity allocation to an active extension allocation of equivalent size generally produces only a very small increase in total portfolio volatility, while the alpha contribution (weighted by the allocation) flows directly to the fund’s expected return. The asymmetry is favourable: a modest increase in tracking error in exchange for a potentially meaningful improvement in expected alpha.

Evidence From the Market

The Goldman Sachs data analysed across global hedge fund-managed beta-1 strategies is instructive. Over the five years to end-2024, active extension products generated annualised excess returns of 5.8%, compared to 2.3% for long-only products—a difference of more than 3.5% per year. The information ratio improvement was also significant, suggesting this outperformance was not simply a function of taking more risk.

In the Australian context, where market concentration is high and sector dynamics are well understood by experienced local managers, the conditions for short alpha generation are arguably even more favourable than in more efficiently priced global markets.

Practical Considerations for Advisors

For advisors considering an active extension allocation, several practical points are worth noting.

  1. Active extension funds can typically sit within the same asset allocation bucket as traditional active equity—they are not alternatives, and do not require reclassification of the portfolio structure. The beta-1 profile ensures the portfolio’s equity exposure target is preserved.
  2. Manager selection is critical. The short book requires genuine skill and operational infrastructure—it is not sufficient to simply be good at picking longs. Advisors should assess a manager’s track record on both sides of the book, their risk management discipline, and their organisational capability to manage short positions efficiently.
  3. Fee structures for active extension products are generally more attractive than equivalent hedge fund offerings, and performance fees—where charged—are typically benchmarked against the equity index, ensuring alignment of interests.

Key Takeaway

Active extension strategies can offer a disciplined, practical way to improve the quality of equity alpha without meaningfully changing portfolio risk. The evidence is clear: more room for alpha opportunities, only marginally more tracking error, and a favourable trade-off at the total fund level. For advisors navigating concentrated markets and persistent long-only headwinds, this approach deserves serious consideration. It’s not about complexity for its own sake—it’s about giving skilled managers the tools to do what they do best.

1. Since 2020
2. Goldman Sachs: Insights in Brief: ‘Beta Times Ahead’, June 2025
3. Morgan Stanley Research, Active Extensions: Alpha Hunting and the Fund Level, December 2006

Disclaimer: This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only.  This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind.  

These materials are not to be distributed and must not be copied, reproduced, published, disclosed or passed to any other person at any time without the prior written consent of Paradice.  

It may contain certain statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these statements.  

The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents and before any action or decision is taken on the basis of this material you should obtain appropriate independent professional advice, as necessary. 

Table of Content

Contributors:

Tom Richardson

Further Information

Beyond the Pledge: How Paradice Puts ESG to Work

This year marks an extraordinary milestone – the 20th anniversary of the Principles for Responsible Investment (PRI). Not only is this a significant milestone for the responsible investment movement more broadly, but it’s also a good moment for us to reflect on what that commitment looks like in practice.

Paradice has been a PRI signatory since 2019, and our commitment has been grounded in a clear conviction that integrating ESG factors into investment analysis is consistent with fiduciary duty. ESG factors can have a real bearing on the long-term financial performance of the companies we invest in and taking them seriously helps us make better informed investment decisions on behalf of our clients.

To mark the occasion, we want to do more than acknowledge the anniversary. Below, we outline the governance structure and policies that underpin how we approach responsible investment at Paradice. We also highlight two multi-year engagements which demonstrate how we put those principles into practice, using our position as an investor to drive meaningful outcomes for our clients and the companies we own on their behalf.

Our Governance Structure

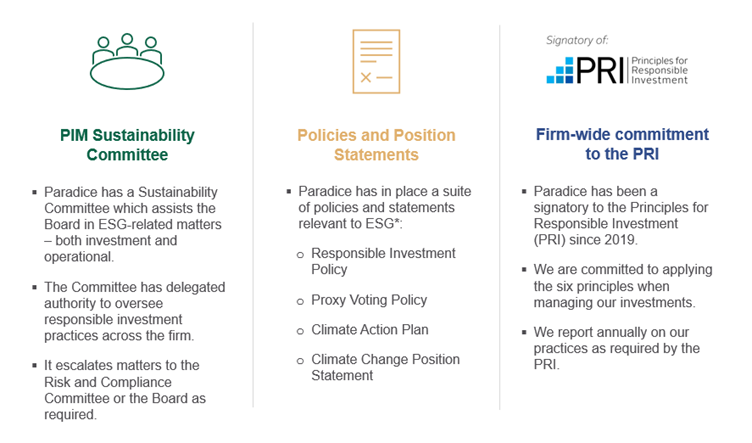
Our approach to responsible investment is built on three pillars: an active Sustainability Committee that oversees our ESG commitments, clear policies and position statements that guide our decision-making, and our firm-wide commitment to the PRI — together forming the governance foundation from which our ESG integration and stewardship activity flows.

Principles in practice

Governance frameworks and policies only mean something if they translate into action. The engagements below span several years and represent some of the more substantive examples of our stewardship in action. An active approach to company engagement is an ongoing and integral part of how we manage our portfolios, and these case studies bring that engagement to life. 

Rio Tinto

The situation: Rio Tinto’s 2020 destruction of Juukan Gorge, and cultural heritage of the PKKP traditional owners, significantly undermined the company’s social licence to operate. It also underscored the importance for companies in the resources sector to have strong relations with their local traditional owners and to appropriately protect cultural heritage. For Rio Tinto in particular, given the failing at Juukan Gorge, it significantly increased its exposure to potential ongoing reputational risks and loss of social licence were it not to significantly improve its approach to cultural heritage. With iron ore operations across the Pilbara impacting the lands of multiple traditional owner groups, including some with Native Title determinations, we thought this necessitated deep and ongoing engagement.

What Paradice did: Immediately after Juukan Gorge, through engagement alongside other shareholders, we sought, what we determined as, appropriate accountability in the first instance, and then a necessary uplift in the company’s approach to managing traditional owner relations and protecting cultural heritage. Overtime our engagement focus shifted to looking for evidence that new ways of working were embedded within operations and that the company had the necessary internal capabilities and expertise. In the last two years, we have been particularly focused on the intersection of cultural heritage and water as we have observed water becoming a priority area for several traditional owner groups. Bodies of water can be sacred sites but are also important to maintaining traditional knowledge and culture. The combination of resource companies’ use of water for their activities with climate change-driven droughts has seen water in the Pilbara become more scarce and contested. We see water efficiency measures and greater use of desalinated water as part of the solution to protect water-related cultural heritage. We have engaged on water and cultural heritage with Rio Tinto multiple times since 2024, including with the Board and Executive Team. We have advocated for the acceleration of the modernisation of its agreements with traditional owners and greater consideration being given to benefits beyond royalty payments. On water, we have encouraged the expansion in capacity of a key project.

What the outcome was: In the months following Juukan Gorge, a commitment to an internal review and leadership change was secured, which saw the resignation of three executives and eventually the Chair. Rio Tinto made changes to its organisational structure to elevate the social performance function and added a director of indigenous heritage to its Board. Over the subsequent four years, Rio Tinto progressively expanded its cultural heritage uplift to its global operations as well. More recently, the company has progressed desalination in the Pilbara. The Dampier Seawater Desalination Plant was initially announced in June 2023 with a planned 4GL capacity. In March 2026, we were pleased to see Rio Tinto announce a joint venture with the WA Government to complete the $1.1 billion plant and expand its capacity to 8GL. Its announcement noted this would “considerably reduce groundwater take and help protect sites of environmental and cultural importance”.1 We continue to engage Rio Tinto on its agreement modernisation process but welcome this significant investment in water.

Santos

The situation: As an oil and gas company producing fossil fuels, Santos sits at the intersection of the energy transition. While its products may still be needed to meet energy demand for decades while systems transform to low carbon sources of generation, Santos must still act to reduce its climate transition-related risks. Of its overall emissions profile, its Scope 3 emissions dominate (those associated with the consumption of its product), but the production of oil and gas still directly generates significant operational emissions (Scope 1 and 2). As these emissions are more within Santos’ control, in our engagement with the company over the past five years we have encouraged it to produce its oil and gas as responsibly as possible.

What Paradice did: In years of engagement with Santos at both the Board and Executive level, we have regularly encouraged the company to invest in emissions reduction initiatives on average meeting four times a year. This has included where this has not been a regulatory requirement and the cost has been material. In our view this is an appropriate mitigation of its transition risk and supports its efforts to maintain social licence. In particular, we have encouraged a beyond-compliance approach to measurement and maintenance in order to reduce fugitive methane emissions (leaks and losses during processing), and that the company pursue carbon capture and storage (CCS) technologies.

What the outcome: We have been pleased to see Santos develop CCS capabilities, in particular through the Moomba CCS facility. Commissioned in 2024, the facility this month recorded 2 million tonnes of carbon stored in its first 18 months of operation, estimated to be the emissions equivalent of taking 826,000 cars off South Australian roads.2 Santos is looking to build a commercial carbon storage business for third-party emissions and has reported capacity to expand CCS at Moomba. Separately, it is advancing a CCS project at Bayu-Undan.

Responsible investment isn’t a destination — it’s an ongoing discipline. The PRI’s 20th anniversary is a reminder of how far the industry has come, but for us the more important measure is what we do year on year as active, engaged owners. These examples are a snapshot of that work. As the expectations on investors continue to evolve, our commitment to meaningful engagement will only deepen.

* The Australian business (Pty) and US business (LLC) have in place different policies and statements, reflecting their different operational jurisdictions.

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only. This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. This material may not represent the views of all investment teams at Paradice. It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct. The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication. The information and opinions contained herein, including information obtained from third party sources which are considered to be reliable, are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents. 

Table of Content

Contributors:

Maddy Dwyer

Further Information

The Case for Long/Short Equity: Understanding Strategies, Approaches & Key Terms

Why Long/Short Equity Matters Now?

Australian advisors and their clients are increasingly asking a pointed question: in a market with no shortage of talented managers, why is consistent outperformance so elusive? The answer lies not in the quality of ideas, but in the structural constraints placed on how those ideas can be expressed.

Traditional long-only funds can only profit when a stock goes up. They are structurally limited in their ability to act on negative views—a manager who believes a stock is overvalued can, at best, hold less of it than the benchmark. This is a significant constraint, and it is one that long/short equity strategies are specifically designed to overcome.

What Is Long/Short Equity?

Long/short equity is a broad category of strategies that hold both long positions (stocks the manager expects to outperform) and short positions (stocks the manager expects to underperform). The short positions are typically funded by borrowing shares, selling them, and seeking to repurchase them later at a lower price. The resulting proceeds can then be reinvested into additional long positions.

This family of strategies spans a wide spectrum, and understanding where a fund sits on that spectrum matters for advisors.

The Spectrum of Strategies

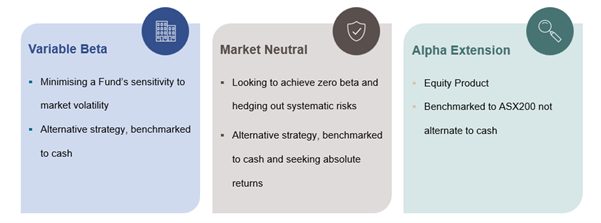
At one end sits the market-neutral fund—constructed to have near-zero net exposure to the market. These funds aim to profit purely from the spread between their long and short books, regardless of market direction. They tend to have low beta, low correlation to equity indices, and are usually housed within alternatives allocations.

At the other end are concentrated long/short funds, which maintain meaningful net long exposure but use shorts to express high-conviction negative views. These can carry significant market sensitivity and behave more like active equity funds with extra tools.

In the middle—and of particular relevance to Australian investors—sits the active extension strategy. Sometimes called a 130/30 (or 135/35, 140/40), these funds maintain a 100% net long exposure to the market, typically benchmarked to an index like the ASX 200. They are permitted to short a defined percentage of the portfolio (say, 30%), with the proceeds reinvested into additional longs (hence “extension”). The result: the same market beta as a traditional equity fund, but a materially expanded opportunity set.


Why Australia Is Well Suited

The ASX 200 is a concentrated index, with the top 10 stocks representing a substantial share of total market capitalisation. In long-only portfolios, underweighting these large-cap names is difficult—there is a limit to how negative you can be on a stock that makes up 8% of the benchmark. Active extension strategies remove this constraint, allowing managers to express their full conviction without the distortions imposed by benchmark composition.


Additionally, Australian markets have historically shown good dispersion at the stock level—meaning individual companies diverge meaningfully in their performance. High dispersion is the environment in which skilled active managers can thrive, and in which short books can add the most value.

Key Takeaway

Long/short equity isn’t always about taking more risk—it’s about removing the structural handcuffs that prevent skilled managers from fully expressing their views. Active extension strategies generally offer the same market exposure as traditional equity funds while significantly expanding the opportunity set for alpha generation. For Australian portfolios navigating a concentrated index, this can be a meaningful advantage.

The structure makes sense on paper—but the proof is in the outcomes. In our next insight, Capturing Alpha, we take a clear-eyed look at the evidence and show how active extension strategies have the potential to strengthen risk-adjusted returns without changing the fundamentals of your equity allocation.

Appendix: Key Terms

  • Net exposure: Longs minus shorts, expressed as a percentage of the portfolio. An active extension fund targets 100% net long—the same as a traditional equity fund (without taking into account the impact of gross exposure and leverage) — making it straightforward to categorise within existing asset allocation frameworks.

  • Gross exposure: Longs plus shorts combined. A 130/30 fund has 160% gross exposure, meaning the total capital at work is greater than the portfolio’s NAV. This leverage is what enables the extended alpha opportunity.

  • Tracking error: Measures how much a fund’s returns deviate from its benchmark. Active extension funds typically have moderate tracking error—higher than an index fund, but often comparable to, or only modestly above, a well-managed active long-only fund. The added tools do not necessarily mean dramatically more risk relative to benchmark.

  • Alpha: The return generated above the benchmark on a risk-adjusted basis. Long/short strategies can generate alpha from both sides: by overweighting stocks that outperform and—as opposed to long only funds—by profiting from stocks that underperform.

  • Short alpha: Often the most underappreciated source of value in these strategies. In Australian markets, where certain sectors have historically exhibited persistent overvaluation or structural decline, the ability to act on these views is genuinely additive.

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only. This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. These materials are not to be distributed and must not be copied, reproduced, published, disclosed or passed to any other person at any time without the prior written consent of Paradice.

It may contain certain statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these statements and before any action or decision is taken on the basis of this material you should obtain appropriate independent professional advice, as necessary.

The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.

Table of Content

Contributors:

Tom Richardson

Further Information

AI and SaaS: Looking Beyond the Hype to the Opportunity

The conversation around AI and software disruption has become increasingly noisy and SaaS company valuations have come under pressure as the market questions how sustainable some business models will be as AI models and agents become more capable. 

Whilst we cannot have certainty, we believe the market may be overestimating the intermediary risk AI poses to many SaaS companies on the ASX200.  In our view AI is a useful tool which enables SaaS to do more with less, rather than replace them entirely and likely places greater emphasis on enduring drivers of business success such as data ownership, regulatory depth and customer trust.  

The “Thin Middle” Squeeze

The old model was simple. Users worked through a SaaS interface—dashboards, workflows, integrations—which sat on top of systems of record holding the underlying data.  

AI is compressing this. Autonomous agents increasingly do the work directly, squeezing the traditional UI layer as value shifts in two directions—up to the AI layer, and down to the systems of record that agents rely on. We think of this as the “thin middle” squeeze. 

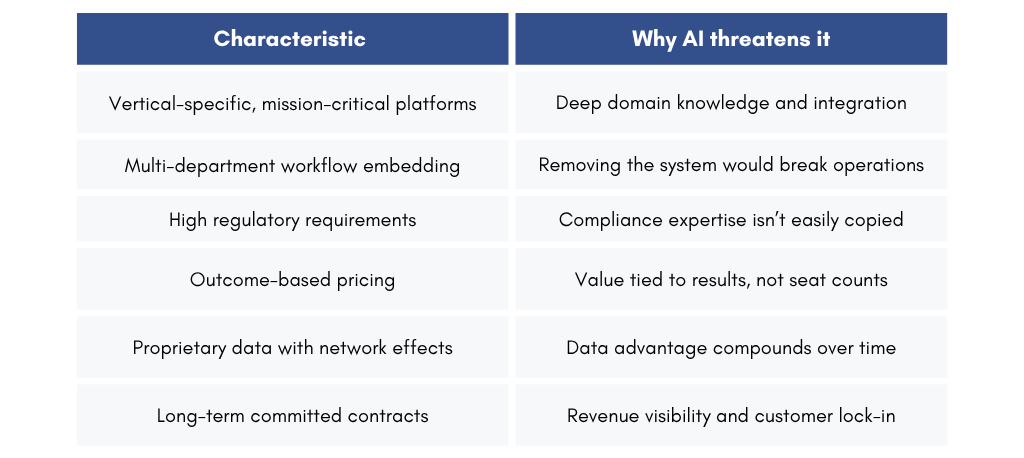
SaaS businesses whose main value is their interface—rather than their data or workflow integration—face the most pressure. 

What AI does and doesn’t disrupt

AI makes it significantly easier to build features. What once took months of engineering can now be prototyped in days. This represents a genuine leap forward in innovation and the speed of product launches. However, AI doesn’t lower barriers to: 

  • Distribution — Reaching customers at scale still needs sales infrastructure, brand recognition, and market presence. You can’t prompt-engineer your way to enterprise relationships. 
  • Data ownership — Proprietary, domain specific datasets built over years of customer activity remain hard to replicate. AI models are only as useful as the data behind them. 
  • Regulatory embedding — Deep compliance knowledge, government relationships, and certification processes take time to build. AI doesn’t shortcut this.
  • Customer trust — Enterprise buyers don’t swap mission-critical systems for a clever new feature. Switching costs, integration depth, and proven reliability still matter. 

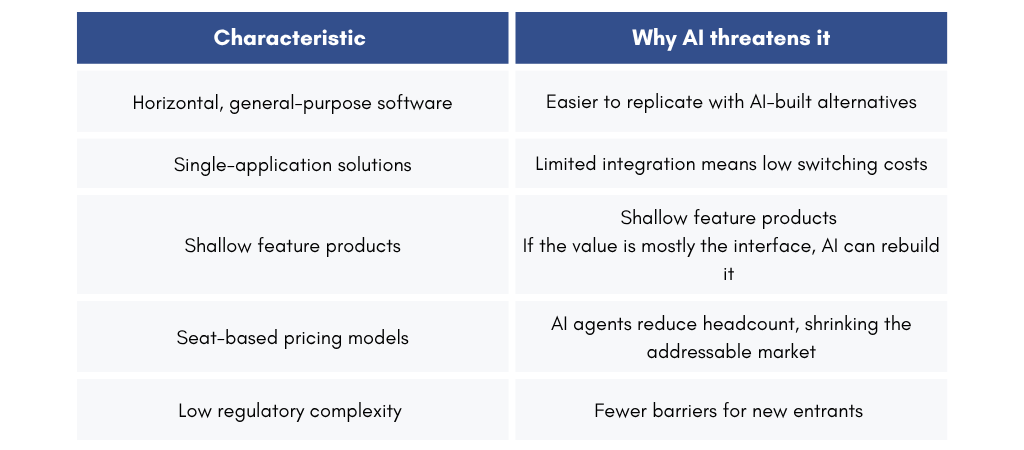
Where we see higher disruption risk: 

Where we see lower disruption risk: 

What we’re seeing in practice

Across our SaaS holdings, we have not seen genuine AI-driven competitive threats emerge. What we’re seeing is the opposite: companies using AI to reinforce their strengths and move faster on product development. We’re seeing this pattern repeat. Businesses with proprietary data, embedded workflows, and real domain expertise are using AI to extend their lead, not defend against erosion. 

Even Anthropic, at “Enterprise Agents” briefing on 24 Feb 2026, highlighted collaboration with leading SaaS companies to further accelerate AI monetisation features.   

We are however mindful that the advent of AI and increased cost of inferencing (querying the underlying data) may lead to SAAS companies having to re-engineer their revenue models. Possible changes could include a move from seat based or per using pricing to a model that captures the value of the work being done and the cost of compute to carry it out. An example of which might be a more transaction-based pricing outcome than a purely per user based model 

We have been selectively adding to SaaS companies within the portfolio as valuation has increasingly become more attractive. For the first time in a long time, some of these companies are growing faster and cheaper than ASX ex Resources, with better cashflow and balance sheet characteristics. 

Disclaimer:

This material is prepared by Paradice Investment Management Pty Ltd (ABN 64 090 148 619 AFSL No 224158) (Paradice, we or us) to provide you with general information only.

This material is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. In addition, this material represents only the views of the Paradice Australian Equities team as at the time of release and is not intended, and may not, represent the views of Paradice or any of the other investment teams at Paradice.

It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.

The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

The information and opinions contained herein, including information obtained from third party sources which are considered to be reliable, are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.

Table of Content

Contributors:

Julia Weng

Further Information

Tom Richardson Discusses His View on How Higher Interest Rates Impact Retail Stocks on ABC News

How higher interest rates impact retail stocks | The Business | ABC News

Tom Richardson discusses his view on how higher interest rates might impact retail stocks with the ABC’s Elysse Morgan.

Watch the interview here

Disclaimer:

This material (or any contribution to it) is not intended to constitute advertising or advice (including legal, tax or investment advice or security recommendation) of any kind.  It is of a general nature only and was current only at the time of initial publication. The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.  It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. You should consider your own needs and objectives and consult with a licensed financial adviser. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.  References to securities may or may not represent the holdings of the Paradice Funds.  The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

Australian Earnings Expectation

Australian Earnings Expectation

Julia Weng (portfolio manager) discusses what she is both looking out for and expecting during reporting season. She speaks with Bloomberg’s Haidi Stroud-Watts and Shery Ahn on “Bloomberg Daybreak: Australia.”

Watch the interview here

Disclaimer:

This material (or any contribution to it) is not intended to constitute advertising or advice (including legal, tax or investment advice or security recommendation) of any kind.  It is of a general nature only and was current only at the time of initial publication. The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.  It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. You should consider your own needs and objectives and consult with a licensed financial adviser. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.  References to securities may or may not represent the holdings of the Paradice Funds.  The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

All the Rage: ESG and the Inevitable Backlash

All the rage: ESG and the inevitable backlash

If you’ve been reading the business pages lately you would be forgiven for thinking that ESG investing – or Environmental, Social and Governance investing – is in the midst of a backlash. Depending on who you ask, this has either been a long time coming or it is an unfair characterisation of a part of the finance industry which is increasingly mainstream. In this month’s newsletter, we thought it would be helpful to demystify ESG (and terms like responsible and sustainable investing which are also used interchangeably) and outline how ESG fits in to investment management at Paradice.  

ESG and responsible investing – what’s the difference? 

Responsible investment or investing is best thought of as an umbrella term for investment strategies which consider ESG-related factors including associated activities such as long-term investing, engagement and voting. Confusingly, though, terms which refer to a specific investment strategy will be used interchangeably with ‘responsible investment’, or ‘ESG’ will be used as a catch-all, adding to lack of clarity on its meaning. 

We find it helpful to think of ESG as an information set (relating to environmental, social or corporate governance matters) which can be variously applied within different investment strategies, depending on an investor’s priorities. For example, in many cases an investor’s focus is to generate risk-adjusted returns. In this case ESG information will be relevant where it may affect a company’s earnings, reputation or liabilities, or other such financially material impacts. A key question in this approach is how does the ESG issue impact the company? 

However, for some investors, they may have additional considerations they would like included in investment decision making. Whether this is motivated by religious beliefs, personal preference or a sense of social responsibility (i.e. values), these investors will look for financial products which in some shape or form limit the investment universe ultimately through the use of ESG-related information. This can be achieved by using such information to either avoid certain types of investments (e.g. products identified as causing social harm such as tobacco), or to actively seek out investments that meet certain characteristics (e.g. a company offering climate solutions or a company whose operations are best-in-class). In contrast to the above, the key question is how does the company impact society or the environment?

Key responsible investment strategies 

The most common strategy in this area is ‘ESG Integration’ and refers to the consideration of financially material ESG factors – both risks and opportunities – within the investment process. The key criteria being that the ESG information is financially material – if it isn’t, it will largely be ignored in investment decision making. For instance, even though climate change may present risks for many companies (and some investors may rightly want to be part of the solution), an investment manager applying an ESG integration approach would only meaningfully consider a company’s greenhouse gas emissions if these were significant enough to present a financial risk. Generally, this will be highly relevant for the energy and heavy industrials sectors, and much less so for professional services and IT as an example.  

If ESG Integration is the strategy which focuses on protecting or enhancing value, the three other core responsible investing strategy types variously incorporate values-based considerations, alongside financial ones. In simplified form, these are: 

  1. Ethical investing: avoiding certain sectors/business activities in line with ethical considerations (e.g. through formal exclusions).  
  2. Sustainable investing: targeting companies with sustainable business practices and/or more sustainable products/services. There is a broad range within this category, with some products much more focused on outcomes with others more aligning to structural trends. 
  3. Impact investing: seeking to achieve targeted and measurable environmental and/or social outcomes (in addition to financial returns). Ideally investments deliver outcomes that wouldn’t otherwise have occurred. 

To add to the confusion, many products will apply more than one strategy at a time. For example, it is common to practice ESG Integration, however this can be supplemented with additional layers of investment decision making such as ethical or sustainable factors. These supplementary layers of decision making may be rules-based (e.g. exclusions), through a structured framework or at the Portfolio Manager’s discretion.  

In our view, common misunderstandings across the market about the nuances of investing for value or to align with values has fuelled some of the current backlash. One outcome has been greater scrutiny of ‘greenwashing’ among stakeholders, and a move for regulators to provide more specific guidelines. We think this will only be positive for the industry, as consumers’ expectations will be better met and true responsible investors will rise to the challenge.

What we do at Paradice  

Paradice strives to be a responsible investor in that we believe it’s important to consider the full range of risks or opportunities that may be financially material to a company and as such we also look to relevant ESG information. In short, Paradice practices ESG Integration in all of our strategies as we strongly believe this helps us to achieve superior risk-adjusted returns for our clients. Besides firm-wide exclusions (tobacco and controversial weapons), currently we do not offer any investment strategies which apply values-based considerations.  

Another reason we consider ourselves to be responsible investors is that we take a longer-term view when investing in portfolio companies. The longer the investment horizon, the more relevant it is to consider ESG information as such issues can often play out over extended time periods. For example, a company cutting corners on safety today will not see this reflected in the share price tomorrow, however, as time passes and safety processes weaken, the greater likelihood a business-disrupting failing will occur. We also see an active approach to company engagement and proxy voting as integral to our active investment management style.

Disclaimer:

This material (or any contribution to it) is not intended to constitute advertising or advice (including legal, tax or investment advice or security recommendation) of any kind.  It is of a general nature only and was current only at the time of initial publication. The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.  It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. You should consider your own needs and objectives and consult with a licensed financial adviser. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.  References to securities may or may not represent the holdings of the Paradice Funds.  The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

3 Preferred Materials Exposures and 1 Sector to Avoid

3 preferred materials exposures and 1 sector to avoid

In a normal cycle, high prices for commodities from high demand would lead to increased supply and finally a drop in prices – but these are far from normal times.

Tom Richardson, Lead Portfolio Manager of the Paradice Equity Alpha Plus Fund, factors like the energy transition, underinvestment in production and ongoing demand from China may see prices rise further, or at least stay higher for longer. He is the first to say this might be a dangerous view and investors should be selective about their commodities investments.

Disclaimer:

This publication is not intended to constitute advertising or advice (including investment advice or security, market or sector recommendations) of any kind. It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. Equity Trustees Limited (ABN 46 004 031 298, AFSL No. 240975) (Equity Trustees) is the responsible entity of, and issuer of units in, the Paradice Funds (Funds). Equity Trustees is a subsidiary of EQT Holdings Limited (ABN 22 607 797 615), a publicly listed company on the Australian Securities Exchange (ASX:EQT). You should consider your own needs and objectives and consult with a licensed financial adviser when deciding whether a Paradice Fund is suitable for you. You should also read the current Product Disclosure Statement and Target Market Determination available at www.paradice.com. References to securities may or may not represent the holdings of the Paradice Funds. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct. The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

5 Stocks on the Energy Transition

5 stocks on the energy transition

Tom Richardson (Portfolio Manager) joined Livewire markets to provide his view of certain energy transition stocks within the Australian energy sector.

Disclaimer:

This material (or any contribution to it) is not intended to constitute advertising or advice (including legal, tax or investment advice or security recommendation) of any kind.  It is of a general nature only and was current only at the time of initial publication. The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.  It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. You should consider your own needs and objectives and consult with a licensed financial adviser. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.  References to securities may or may not represent the holdings of the Paradice Funds.  The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

The Party in Commodities Isn’t Over

The party in commodities isn’t over

Tom Richardson (Portfolio Manager) joined a thematic discussion with Livewire Markets on the commodities cycle, where he was asked to provide his views on some specific Australian materials, miners and explorers stocks.

Disclaimer:

This material (or any contribution to it) is not intended to constitute advertising or advice (including legal, tax or investment advice or security recommendation) of any kind.  It is of a general nature only and was current only at the time of initial publication. The information and opinions contained herein are not necessarily all-inclusive and, as such, no representation or warranty, express or implied, is made as to the accuracy, completeness or reasonableness of any assumption contained herein and no responsibility arising for errors and omissions (including responsibility to any person by reason of negligence) is accepted by Paradice, its officers, employees or agents.  It may contain certain forward looking statements, opinions and projections that are based on the assumptions and judgments of Paradice with respect to, among other things, future economic, competitive and market conditions and future business decisions, all of which are difficult or impossible to predict accurately and many of which are beyond the control of Paradice. Because of the significant uncertainties inherent in these assumptions, opinions and judgments, you should not place undue reliance on these forward looking statements. You should consider your own needs and objectives and consult with a licensed financial adviser. For the avoidance of doubt, any such forward looking statements, opinions, assumptions and/or judgments made by Paradice may not prove to be accurate or correct.  References to securities may or may not represent the holdings of the Paradice Funds.  The content of this publication is current as at the date of its publication and is subject to change at any time. It does not reflect any events or changes in circumstances occurring after the date of publication.

Paradice Investment Management Logo_CMYK White-Gold_RGB_FIN

Subscribe to our newsletter for updates.

logo-black

Welcome to Paradice Investment Management

Visit our site for individuals and financial advisors.

Visit our site for institutional investors.